Этот материал пока доступен только на языке: английский — перевод ещё не готов.
The Airbus Loan Washington Noticed: How €3 Billion Became a Trade Weapon
A European Investment Bank credit line to Airbus has given the US Trade Representative a lever on the tariff truce. The question is whether Brussels understood that when it signed.
The United States Trade Representative, Jamieson Greer, chose his verb with care on Monday. The June financing from the European Investment Bank to Airbus, he said, 'injects substantial uncertainty into transatlantic trade in the aerospace sector.' Injects. Not threatens, not endangers — injects. The word treats the loan as a foreign substance introduced into an otherwise functional body. Readers who follow the choreography of trade enforcement will recognise the construction: it is the vocabulary a trade representative uses when he intends to open a file, not when he intends to close one.
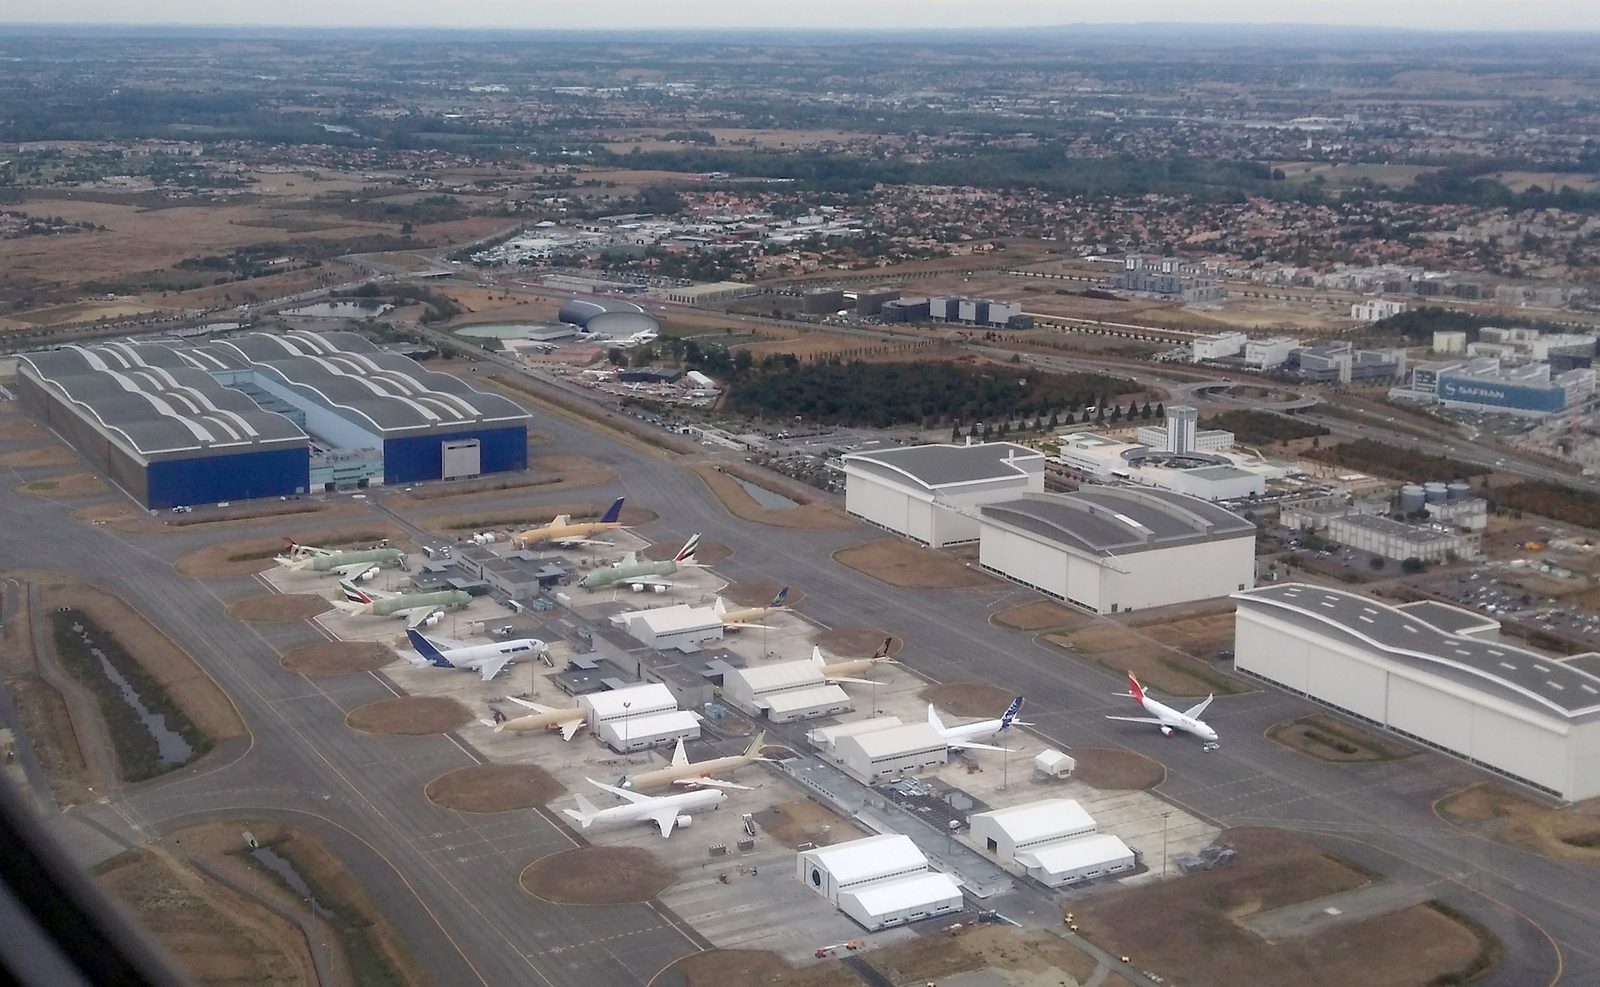
The operative facts are narrow. In June, the European Investment Bank announced three billion euros — roughly 3.4 billion dollars — in financing to Airbus for research, development and innovation across civil aviation and the defence sector. The Bank's vice president called it 'unprecedented in the EIB's history.' The 2021 truce negotiated under the previous US administration had quietly ended seventeen years of Boeing-Airbus litigation at the WTO without resolving the underlying question: what counts as a legitimate public investment in a strategic industrial champion, and what counts as a prohibited subsidy. The truce did not answer. It simply suspended the tariffs and left the definitional fight for another day. Monday was that day.
My reading is that the EIB operation was designed in Luxembourg to look like what it is on paper — a loan at commercial terms to a creditworthy borrower for R&D, which is exactly the kind of transaction the Bank's statute envisages. But paper is not politics. The size matters. The dual-use framing — civil aviation and defence — matters more. By bundling commercial aerospace with security and defence investments into a single headline figure, the June announcement handed the USTR a ready-made argument: that European public money is being routed through an institutional vehicle to cross-subsidise the commercial side. Whether that argument is true under WTO jurisprudence is a question for lawyers. Whether it is useful to Washington today is a question that answers itself.
Who wrote this compromise inside the Union? The EIB does not lend on political whim; it lends on mandates shaped by shareholders, and the shareholders are the member states. The French and German governments have an obvious interest in Airbus financing, and both capitals have spent the past year insisting that European industrial autonomy requires public credit at a scale American and Chinese competitors take for granted. The Commission's own doctrine — the competitiveness compass, the Draghi follow-through, the whole architectural turn toward 'strategic autonomy' — has given political cover to exactly this kind of transaction. What nobody in Brussels appears to have costed into the file is the extraterritorial price: that a transatlantic tariff truce held together by nothing more than mutual restraint can be reopened by any American administration that finds the right pretext.
And this is where the EU-Gulf transmission becomes concrete. Gulf carriers and sovereign funds with substantial Airbus order books and equity exposure read Mr Greer's statement on Monday the way they read every USTR communication: as a probability update on tariff reinstatement. If the 2021 truce collapses, the aircraft delivery schedules that anchor fleet planning from Doha to Dubai acquire a new layer of political risk. Gulf finance ministries do not need a Commission briefing to understand that the EIB's industrial policy choices are now their currency hedging problem.
Enforcement is the test. Here, enforcement runs in two directions. On the American side, the USTR has the Section 301 toolkit and the discretion to apply it; the warning shot is the enforcement, in that it extracts information and concessions without any formal proceeding. On the European side, enforcement means something quieter: whether the Commission's trade directorate will now review future EIB operations for their transatlantic exposure before they are announced, or whether the Bank will continue to operate on the premise that its mandate is a European matter and Washington's reaction is somebody else's problem.
The pattern I see is this. The Union has spent two years building instruments — the Digital Markets Act, the AI Act, the carbon border mechanism, now a muscular EIB — designed to project European preferences outward. Each instrument assumes that the external response will be managed through dialogue. Mr Greer's statement is a reminder that the external response is managed through leverage, and that a tariff truce is a form of leverage the other side can withdraw.
The Airbus loan was a decision somebody made in June. The invoice arrived in October.